October 2026, Edition 3
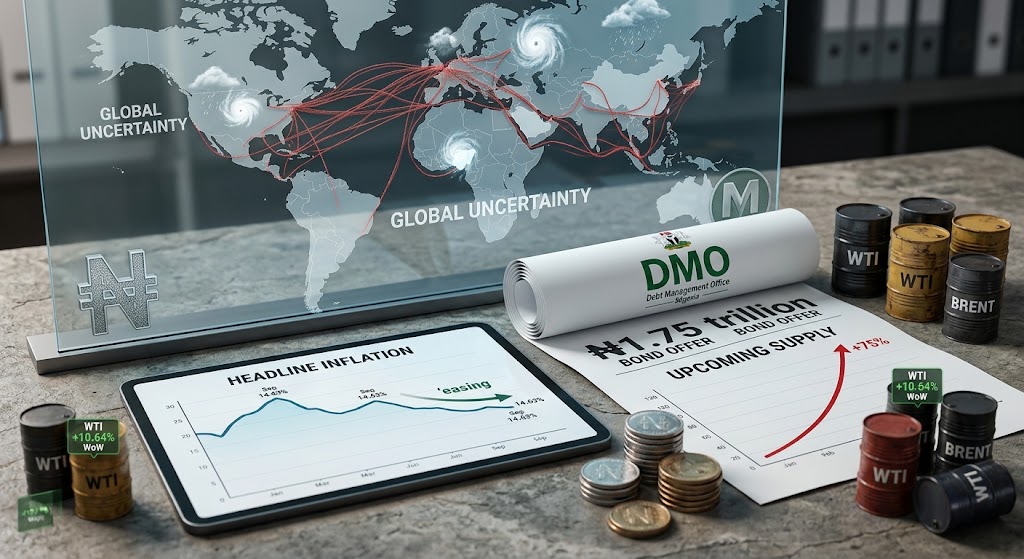
Nigeria’s financial markets navigated a week of divergent signals as persistent selling pressure in FGN bonds and selective repricing across money-market instruments contrasted with strong demand for longer-dated Treasury bills and easing domestic inflation. September headline inflation moderated to 14.63%, supporting the case for improved real returns, while substantial Q4 FGN bond issuance and a 75% increase in the October offer reinforced concerns over supply-driven yield volatility. The Naira remained broadly stable amid gradually rising external reserves, while equities showed limited resilience through selective sectoral buying despite negative weekly performance across most indices. Beyond domestic markets, renewed US inflationary pressure, elevated global bond yields and oil-market uncertainty complicated the outlook for monetary easing and investor risk appetite. Overall, the week highlighted a market balancing improving domestic macroeconomic indicators against heavy sovereign supply, uneven liquidity transmission, and persistent global uncertainties. In commodities, prices closed higher Week-on-Week (WoW) at $101.41/bbl. (+10.64%) and $109.86/bbl. (+5.20%) for West Texas Intermediate (WTI) and Brent crude, respectively, while gold was at $4,166.39/oz. (-0.64%).
System liquidity rose by 55.42% WtD, opening at ₦4.02 trillion, peaking at ₦6.49 trillion on Tuesday, supported by ₦2.41 trillion in OMO maturity inflows, before closing at ₦6.28 trillion. Money market rates eased modestly, with the Open Repo Rate (OPR) and Overnight (O/N) rate closing at 20.38% (-40bps) and 20.35% (-47bps), respectively. In the Foreign Exchange (FX) market, the Naira traded within a range of $/₦1,327.00 and $/₦1,336.00, before closing at $/₦1,332.26 on Friday.
The fixed-income secondary market showed divergent performance across the week, seasoned with bearish energy, with a bullish tilt on Thursday after the inflation report release as investors reassessed entry levels across Treasury bills (T-bills), Open Market Operations (OMO) bills and FGN bonds. OMO instruments showed divergent pricing, with offers easing to around 16.85% on Thursday for the 9-Feb-2027 bill, while the Dec-2026 bill offers rose from 18.25%–18.45% on Monday to 18.50%–18.65% on Tuesday and Wednesday, reflecting continued demand for higher yields at the short end. T-bills witnessed marginal demand, with average yields inched up marginally by +2bps to 17.98%, despite intermittent pressure on selected maturities, particularly the 03-Jun-27 and 23-Sep-27 papers, while broad-based buying persisted across the curve of the money market. In the FGN bond segment, offers generally repriced upward early in the week, with the Jun.-2038 issue seeing bids reach 17.56% on Tuesday before moderating to around 17.10 on Friday. Selective activity was prominent in the 2033s–2038s, with the 2034s up 59bps to 17.00%; the move suggests selective buying at improved yield levels alongside persistent selling pressure and wide bid-offer spreads.
FGN Bond Issuance Update: The Debt Management Office (DMO) announced a ₦1.75 trillion offer for FGN bond auction scheduled for October 19, 2026, comprising three reopened instruments: the 19.00% FGN February 2034, 16.79% FGN September 2036, and 15.45% FGN June 2038 bond with individual offers of ₦500 billion, ₦800 billion and ₦450 billion, correspondingly. Notably, the total offer was up by 75% from the previous auction, signalling higher government borrowing that could put upward pressure on secondary-market yields where demand falls short of the expanded issuance. The DMO has also released its provisional Q4 2026 issuance calendar, indicating a 74.2% increase in planned offer volume to ₦5.75 trillion from that offered in Q3 2026. Monthly issuance is scheduled at ₦1.75 trillion in October and ₦2.00 trillion each in November and December. By instrument, the September 2036 bond accounts for the largest share at ₦2.80 trillion, followed by the February 2034 bond at ₦1.50 trillion and the June 2038 bond at ₦1.45 trillion. The increased issuance could sustain yield pressure, with auction outcomes dependent on investor appetite, liquidity conditions, and pricing.
NTB Issuance: The 14 October 2026 auction reflected strong but highly selective demand, with total subscriptions of ₦1.03 trillion against ₦450.0 billion offered, representing an aggregate bid-to-cover ratio of 1.02x, 1.02x, and 4.46x for 91-. 182-, and 364-day bills, respectively, while 26.1% of total subscriptions were allotted. Demand was concentrated in the 364-day bill, which attracted over 2.81x against ₦350 billion offered, with 0.63x allotted, compared with weaker demand for the 91- and 182-day bills at 0.39x and 0.60x, respectively, against their respective offers. Stop rates on the short- and mid-day bills remained unchanged at 15.50% and 15.80%, respectively, while the 364-day stop rate increased by 5bps to 15.90% from 15.85%, indicating a modest bearish repricing in longer-duration paper. Overall, the auction points to strong issuer-inclined selective allotment, maintaining its benchmark amidst the strong demand on the 1-year bill.
AUCTION DATE | 14-10-2026 | 14-10-2026 | 14-10-2026 |
MATURITY DATE | 14-01-2027 | 15-04-2027 | 14-10-2027 |
TENOR | 91-DAY | 182-DAY | 364-DAY |
OFFER (₦) | 50,000,000,000 | 50,000,000,000 | 350,000,000,000 |
SUBSCRIPTION (₦) | 19,907,460,000 | 30,104,416,000 | 982,207,263,000 |
ALLOTMENT (₦) | 19,521,460,000 | 29,544,416,000 | 219,996,904,000 |
BID RANGE (%) | 15.3800 – 17.0000 | 15.2500 – 16.5000 | 15.0000 – 18.1800 |
STOP RATES (%) | 15.5000 | 15.8000 | 15.9000 |
PREVIOUS STOP RATES (%) | 15.5000 | 15.8000 | 15.8500 |
According to the National Bureau of Statistics (NBS) Consumer Price Index Report for September 2026, Nigeria’s disinflation momentum is strengthening, with headline inflation easing to 14.63% year-on-year (YoY) from 15.39% in August and MoM inflation slowing to 0.06% from 0.71%. Food inflation stood at 19.59% YoY, with a -1.55% MoM decline, while core inflation moderated to 12.95% YoY, despite a 1.11% MoM rise, indicating continued underlying price pressures. For fixed income, the data supports duration extension and yield-locking, with lower headline and food inflation improving real yields, with real rate of return at 8.37%, and potentially strengthening demand for sovereign assets. However, the rise in core inflation limits the case for aggressive monetary easing. Fixed-income yields could face further downward pressure, subject to system liquidity, issuance supply and MPC guidance. The disinflationary trend also does not imply lower living costs, as accumulated food, energy, transport and housing costs remain elevated, albeit with slower price increases.
The Naira declined a bit during the week in the Nigerian Foreign Exchange Market (NFEM), losing 0.16 (+0.01%) WtD, and ₦1.07 (+0.08%) WoW, closing at $/₦1,332.26 (WoW: $/₦1,331.19). Foreign reserves increased from $55.07 billion to $55.09 billion (+0.04%) as of October 15, 2026, despite an intra-week peak of $55.10 billion, while blocked funds improved by 0.27% to $504.21 million from $502.86 million, with the blocked reserve ratio steady at 0.92% (+1bps), indicating improved foreign exchange conditions and receipts amidst external pressures.
Other developments: Nigeria’s capital and corporate markets recorded several developments with implications for investor confidence and capital mobilisation: the Nigeria Energy Sector Fund announced a ₦383.00 per-unit distribution to eligible unitholders, with electronic payment scheduled for October 21, reinforcing the fund’s focus on returning value from its energy-sector and fixed-income exposures. Fitch Ratings revised the outlooks of 11 Nigerian banks and bank-related institutions to Positive from Stable, following its positive revision of Nigeria’s sovereign outlook, citing the Naira’s appreciation, stronger reserves, easing inflation and improved policy credibility; however, the banks remain exposed to sovereign risk, with further upgrades dependent on sustained improvements in Nigeria’s credit profile and individual lenders’ capital and asset-quality positions. In the energy sector, Dangote Petroleum Refinery extended its initial public offering (IPO) application by 10 days to close on October 27, 2026, to broaden participation among African investors, with the offering targeting $1.6 billion and potentially $2.1 billion with the over-allotment option; the extension comes as the refinery reported a sharp turnaround to $4.73 billion net profit for January–September 2026, strengthening the investment narrative around the planned expansion. Meanwhile, Shell agreed to sell its entire interest in Shell Nigeria Gas Group to Vaaris Energy, subject to regulatory approvals, marking another portfolio simplification as Shell retains its focus on deepwater and integrated gas assets; the transaction transfers a domestic gas-distribution business operating about 170km of pipeline infrastructure across Ogun, Abia and Rivers States to Nigerian ownership.
Global financial markets during the week ended October 16, 2026, were heavily anchored by critical inflation releases, energy market realignments, and high-level policy discussions at the 2026 IMF–World Bank Annual Meetings. In the United States, according to the Bureau of Statistics, 2headline inflation accelerated to 3.7% YoY in September following a 0.6% monthly surge in consumer prices driven primarily by rising energy and fuel costs, rekindling expectations of tighter monetary policy and fuelling a broader Treasury market sell-off at elevated sovereign yields (U.S. 10-year at 5.09%, U.K. 10-year Gilt at 5.38%), and the Organization of the Petroleum Exporting Countries’ (OPEC) downgraded demand forecast (0.2 mb/d). Meanwhile, China’s National Bureau of Statistics, inflation showed modest firming, with September inflation rising 0.9% from 0.8% in August, while its Producer Price Index (PPI) surged to 5.0% year-over-year on elevated international energy import costs. Adding to commodity market shifts, Organization of the Petroleum Exporting Countries’ (OPEC) lowered its 2026 global oil demand growth forecast to 0.2 million barrels per day (mb/d), reflecting soft consumption in Organisation for Economic Co-operation and Development (OECD) economies and selective adjustments across major importers. Concurrently, delegates at the IMF Annual Meetings highlighted that while global growth remains resilient at a projected 3.1% for 2026, narrowing fiscal buffers, depleted emergency energy stocks, and AI-driven tech sector concentration mean the global economy is rapidly testing the limits of its resilience. The equities market performance closed mixed WoW; the Nasdaq Composite at 26,140.03 (-4.48%), the S&P 500 at 7,659.44 (-1.95%), and the Dow Jones Industrial Average at 52,002.41 (+0.67%). Across Europe, Germany’s DAX 40 was at 25,622.61 (+2.13%), while the FTSE 100 was at 10,881.90 (+3.10%), and the Stoxx 600 at 644.74 (+2.09%). Asian markets were mixed, with Japan’s Nikkei 225 at 65,324.29 (-5.37%), China’s Shanghai Composite Index at 3,716.28 (-2.56%), Hong Kong’s Hang Seng Index at 24,186.83 (+0.10%), and South Korea’s KOSPI at 5,668.05 (-14.46%).
Global commodities traded with heightened volatility during the week as geopolitical risks, monetary-policy expectations and supply concerns shaped investor sentiment. Oil prices strengthened sharply early in the week, with WTI rising from $91.85/bbl to above $93.80/bbl., and Brent climbing from $104.72/bbl. to above $109/bbl. on renewed attacks in Ukraine and the Middle East and heightened risks around the Strait of Hormuz; prices subsequently consolidated before WTI corrected below $94/bbl. on Thursday amid potential easing of sanctions on Russian “shadow fleet” vessels, while Brent remained supported by escalating Middle East tensions and an 8.6 million-barrel decline in US crude inventories. By Friday, WTI closed at $101.41/bbl., up about 6% for the week, while Brent closed at $109.86/bbl., remaining on course for a weekly gain, supported by shipping disruptions, renewed regional attacks and tighter physical-market risks; the International Energy Agency’s (IEA) decision to release the remaining 100 million barrels from its coordinated intervention provided some counterweight. Gold, meanwhile, was initially pressured by a stronger US dollar and rising rate expectations, falling from $4,193.87/oz to $4,083.22/oz after hotter-than-expected US September inflation reinforced expectations of tighter Fed policy, before recovering on safe-haven demand amid equity-market weakness and geopolitical tensions; bullion closed Friday at $4,166.39/oz, recovering strongly but still below the week’s opening level.
The new week is poisitioned to be a heavy week, with the scheduled October 2026 FGN Bond Auction following the sixth cooling inflation print of the year, with headline inflation at 14.63%; the ripple effect is anticipated in robust demand. Nigeria is expected to receive liquidity inflows of more than ₦2.76 trillion, comprising ₦2.07 trillion from OMO maturities, NTB maturities of ₦392.80 billion, and ₦297.86 billion from coupons payment on FGN 16.2499% Apr. 2037. Thereby supporting the already substantial liquidity surplus that could influence money-market rates, asset allocation, and the direction of fixed-income yields.
By: Sandra A. Aghaizu
Money returns like rivers to the shore,
While cooling inflation opens another door.
Bonds await investors, their yields in the balance,
As capital moves in search of greater returns.
Trillions flow, and markets rearrange,
With every new inflow, the currents may change.
For where money settles, new prices take flight,
And liquidity quietly steers the market’s tide.

Subscribe now to keep reading and get access to the full archive.