Period: November 04 – 11, 2026
The cryptocurrency market entered another phase of correction during the week, as the optimism that followed the U.S. midterm elections gave way to renewed macroeconomic anxiety and intensifying institutional competition. Bitcoin (BTC) retreated towards $73,000, Ethereum (ETH) traded around $2,000, while Solana (SOL) slipped towards $83, reversing much of the market’s earlier recovery. The sell-off reflects a deterioration in risk appetite as rising U.S. Treasury yields, persistent inflationary pressures and increasingly hawkish Federal Reserve signals weighed on speculative assets. Adding another dimension to the market’s uncertainty, a consortium of major global financial institutions committed approximately $270 million to a proposed stablecoin venture, reinforcing Wall Street’s ambition to establish a stronger foothold in digital financial infrastructure. Together, these developments highlight a market increasingly caught between restrictive macroeconomic conditions and the institutionalisation of digital assets.
The resurgence in U.S. bond yields has emerged as a significant headwind for digital assets. October’s U.S. Consumer Price Index (CPI) report recorded a 0.4% monthly increase, exceeding market expectations of 0.3%, reinforcing concerns that inflationary pressures remain persistent. Although the absence of a comparable year-on-year figure complicates the inflation assessment, the latest reading has strengthened the case for continued monetary restraint.
Federal Reserve Governor Christopher Waller subsequently indicated support for a 25-basis-point policy rate increase at the upcoming December 8–9 Federal Open Market Committee (FOMC) meeting, while leaving room for a more aggressive response should inflation materially exceed expectations. His remarks reinforced market expectations of further tightening, although the eventual policy decision remains contingent on incoming economic data.
Bond markets responded sharply, with the benchmark 10-year U.S. Treasury yield briefly exceeding 5.00% on November 10, reaching approximately 5.01%, before its latest reported close settled just below that threshold. The renewed rise in benchmark yields increases the opportunity cost of holding non-yielding assets, particularly cryptocurrencies, while tightening broader financial conditions. Consequently, digital assets remain vulnerable to further downward repricing should yields sustain their upward trajectory.
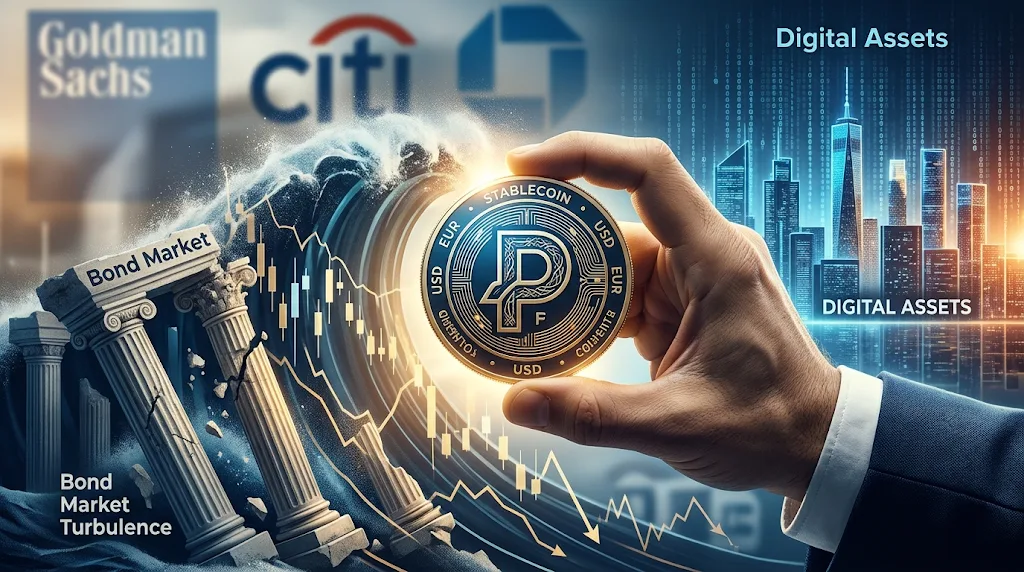
Beyond monetary policy, the growing involvement of traditional financial institutions in digital assets is introducing a structural shift in the competitive landscape. A consortium involving Goldman Sachs, Citigroup, Banco Santander and Deutsche Bank, alongside other global financial institutions, has reportedly committed approximately $270 million towards the development of a jointly backed stablecoin venture, operating under the codename Project Faro.
The funding is expected to cover the venture’s first five years of operating costs, signalling a longer-term strategic commitment rather than a limited proof-of-concept initiative. The proposed issuer intends to launch a dollar-denominated stablecoin, with ambitions to extend into other major currencies, including the Euro. Its targeted commercial rollout is the first half of 2027.
The development represents more than another institutional cryptocurrency initiative. It signals a direct move by established financial institutions into a market historically dominated by crypto-native issuers such as Tether (USDT) and Circle (USDC). With their established banking relationships, regulatory infrastructure, balance sheets and institutional distribution networks, participating banks could introduce formidable competition in payments, cross-border settlement and tokenised financial transactions.
However, the venture’s commercial success will depend on regulatory execution, interoperability, adoption and the ability to compete on liquidity and settlement efficiency. For existing stablecoin issuers, the challenge is no longer limited to regulatory scrutiny; it increasingly involves defending market share against institutions with substantial financial and distribution capabilities.
The broader market correction reflects weakening investor conviction, with BTC’s retreat exerting pressure on major altcoins. Ethereum’s inability to sustain higher price levels and Solana’s decline below $83 further illustrate the vulnerability of assets with higher sensitivity to changes in risk appetite.
Asset / Index | Spot Price | Support Zone | Resistance Zone | Bias |
Bitcoin (BTC) | ~$73,700 | $70,000–$71,500 | $77,500–$80,000 | Bearish |
Ethereum (ETH) | ~$2,060 | $1,920–$1,980 | $2,250–$2,380 | Bearish |
Solana (SOL) | ~$83.50 | $75–$80 | $92–$98 | Bearish |
Total Crypto Market Cap | ~$2.54tn | $2.40tn | $2.75tn | Bearish |
Bitcoin’s immediate technical outlook remains cautious. A sustained break below the $70,000 psychological threshold could expose the asset to deeper downside, with the $65,500–$68,000 region representing a potential demand zone. Conversely, a recovery above $77,500 would be necessary to improve near-term market structure and reopen the path towards $80,000.
Ethereum remains under pressure around the $2,000 psychological level. A decisive loss of the $1,950 support region could expose prices to the $1,750–$1,820 range, while a recovery above $2,150 would improve the immediate outlook. Solana’s ability to defend the $75–$80 support band will similarly be critical in determining whether the current correction develops into a deeper retracement.
The near-term outlook remains tilted towards downside risk, although the extent of further losses will depend on macroeconomic developments, Treasury yield movements, institutional fund flows and broader market liquidity. Three scenarios provide a framework for assessing potential price direction.
The cryptocurrency market is confronting a defining intersection between macroeconomic repricing and institutional transformation. Elevated Treasury yields continue to challenge the valuation appeal of non-yielding digital assets, while the growing participation of global banks in stablecoin development signals an increasingly competitive institutional landscape. These forces are not necessarily contradictory: institutional adoption may strengthen the long-term foundations of digital finance even as tighter financial conditions undermine short-term asset valuations.
For investors, the immediate priority remains capital preservation, disciplined positioning and close monitoring of key technical support levels, Treasury yields and institutional capital flows. A sustained recovery will require more than election-driven optimism; it will depend on improving liquidity conditions, renewed risk appetite and evidence that selling pressure is abating.
Ultimately, Wall Street’s growing ambitions in stablecoins may represent a structural positive for the broader digital asset ecosystem, but they do not provide an immediate floor for cryptocurrency prices. Until macroeconomic conditions become more supportive, the market is likely to remain volatile, selective and vulnerable to further downside repricing.
By: Sandra A. Aghaizu
Loading…
Subscribe now to keep reading and get access to the full archive.