November 2026, Edition 3
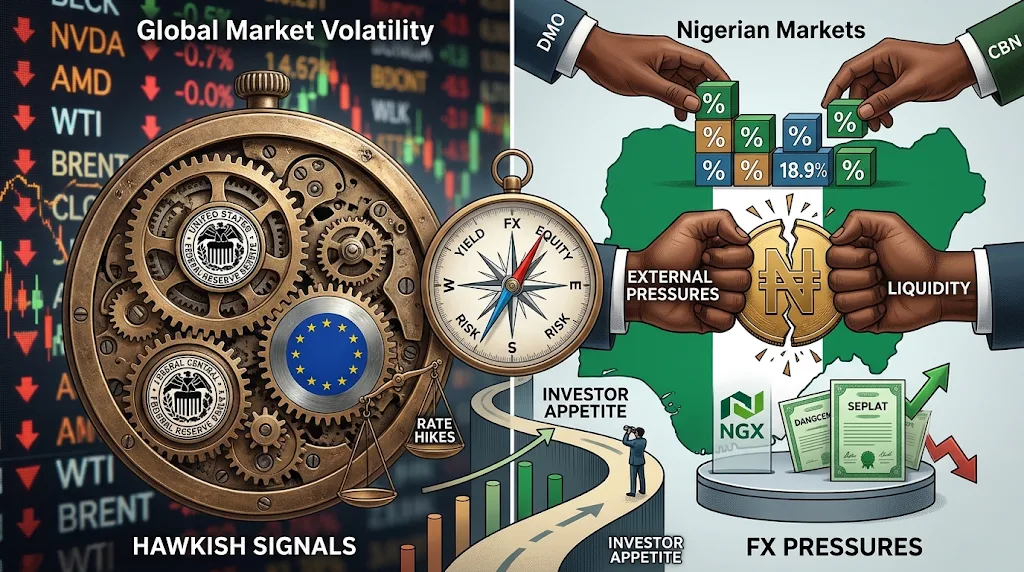
Nigerian financial markets recorded divergent asset-class performance during the week, as sustained demand for mid- to long-dated fixed-income securities and selective equity buying contrasted with renewed pressure on the Naira and external reserves. In the fixed-income market, bullish secondary-market sentiment persisted across short- to mid-tenor maturities, with yields easing towards 16.65%–16.75%, despite pockets of selective selling pressure following the Debt Management Office (DMO) revised Q4 issuance calendar. Meanwhile, the Central Bank of Nigeria (CBN) maintained its aggressive liquidity sterilisation stance, allotting ₦3.85 trillion at its Open Market Operation (OMO) auction against subscriptions of ₦4.07 trillion. The Nigeria Treasury Bills (NTB) auction also revealed a pronounced preference for the 364-day instrument, which accounted for 96.2% of total subscriptions, highlighting investors’ appetite for longer-date carry opportunities. In the foreign exchange market, the Naira depreciated by 0.34% week-to-date (WtD) at the Nigerian Foreign Exchange Market (NFEM), while external reserves declined by 0.47% to $54.87 billion, reflecting persistent external liquidity pressures. Conversely, the Nigerian Exchange (NGX) All-Share Index (ASI) advanced by 1.56% to 252,749.79 points, expanding market capitalisation by ₦2.52 trillion to ₦164.80 trillion and lifting YTD returns to 62.42%, supported by renewed bargain hunting in selected large-cap stocks despite profit-taking and competing liquidity demands. Globally, financial markets experienced heightened volatility amidst hawkish inflation signals, rising sovereign bond yields and renewed uncertainty in the technology-sector, while commodity prices extended losses amid shifting supply dynamics and changing interest-rate expectations.
In the commodity market, prices closed lower week-on-week (WoW) at $88.56 /bbl. (-2.50%) and $95.84/bbl. (-2.52%) for West Texas Intermediate (WTI) and Brent crude, respectively, while gold declined to $3,881.75/oz (-4.63%).
System liquidity eased by 34.74% WtD, opening at ₦6.09 trillion, peaking at ₦8.31 trillion on Tuesday before closing at ₦3.94 trillion. Liquidity built up on inflows of ₦2.45 trillion, including OMO and NTB maturities, while outflows exceeded ₦4.57 trillion, largely attributable to OMO and NTB issuances. Money market rates recorded movements, with the Open Repo Rate (OPR) and Overnight (O/N) rate closing at 20.00% (unchanged) and 20.43% (+23bps), respectively. In the Foreign Exchange (FX) market, the Naira traded within a range of $/₦1,346.30 and $/₦1,365.00 before closing at $/₦1,353.97 on Friday.
The fixed-income secondary market sustained a bullish bias, supported by demand for mid- to long-dated FGN bonds, particularly the 2033–2038 maturities, while the short end (2027–2029 maturities) faced pockets of selling pressure following the DMO’s revised Q4 issuance calendar. Bond yields initially declined by 12bps to 16.83%, moderating further to the 16.65%–16.75% range towards the week’s close, reflecting sustained buying interest despite emerging supply concerns. Similarly, OMO and NTB instruments recorded yield compression, with the 01-Dec-2026 OMO bill trading at 17.20% and the 04-Nov-2027 and 11-Nov 2027 NTB bills traded at 15.50%, and 15.85%, respectively, reflecting continued interest in relatively attractive carry opportunities. Overall, trading sentiment remained selective and sensitive to prospective supply and prevailing yield levels, with demand supporting prices across the mid-to-long end, while expectations of higher issuance and prevailing yield thresholds continued to shape positioning.
Money Market Issuance: The CBN’s November 10, 2026 OMO auction offered a total of ₦1.50 trillion split equal across three tenors, each instrument with maturity of at least 18 days shorter than its respective previous auction comparator, reinforcing the Bank’s active yield management and liquidity sterilisation stance. Despite elevated system liquidity, which peaked above ₦8.31 trillion, demand remained strong, with total subscriptions reaching ₦4.07 trillion against total allotment of ₦3.85 trillion. Stop rates settled at 17.44%, 16.68%, and 15.99% for the 154-, 252-, and 329-day bills, respectively, while the corresponding bid-to-cover ratios stood at 1.63x, 1.01x, and 1.01x. The substantial allotment relative to subscriptions highlights the CBN’s continued absorption of excess Naira liquidity to contain monetary and exchange-rate pressures. However, effective yields remained broadly stable at 18.83% (-1bp), 18.85% (unchanged), and 18.62% (-2bps), respectively, indicates marginal or no adjustments in implied market returns. The true yield shows little or no movement, which gives a firm stance of the government as it tries to restrict/manage returns at a stable level.
AUCTION DATE | TENOR | OFFER (₦‘ B) | BIDS (₦‘ B) | TOTAL SALE (₦‘ B) | STOP RATES (%) | PREVIOUS TENOR RANGE STOP RATES (%) |
10-11-2026 | 154-DAY | 500.00 | 457.89 | 280.76 | 17.4400 | 17.2500 |
252-DAY | 500.00 | 791.50 | 783.50 | 16.6800 | 16.5400 | |
329-DAY | 500.00 | 2,824.49 | 2,789.49 | 15.9000 | 15.7400 |
NTB Issuance: The November 11, 2026, auction revealed a selective demand for the 1-year bill, which attracted over 1.08 trillion in demand, marking 96.2% of total subscriptions of ₦1.12 trillion against the ₦800 billion aggregate offer. In contrast, the 91- and 182-day bills recorded weak demand at 0.19x and 0.23x, while the 364-day outperformed at 1.79x. translating to a bid-to-cover ratio of 1.06x, 1.03x, and 1.60x for the 91-, 182-, and 364-day bills, respectively. Allotment to offer ratio was at 0.18x, 0.22x, and 1.21x. Total sales were ₦713.30 billion, representing nearly 63.6% of total demand, with the 1-year bill being 94.3% of the total volume, reflecting the CBN’s selective allotment despite strong demand, compared to weaker interest in the 91- and 182-day bills. Stop rates held steady for the short- and mid-day bills, while the long-day improved by 9bps to 18.89%. Effective yield improved to 18.88% (+12bps) for the 1-year bills, while the short- and mid-day bills were unchanged at 16.01% and 17.14%. Overall, the auction highlights the issuer’s continued selective allotment strategy, maintaining the rate threshold amid strong demand at the long end.
AUCTION DATE | 11-11-2026 | 11-11-2026 | 11-11-2026 |
MATURITY DATE | 11-02-2027 | 13-05-2027 | 11-11-2027 |
TENOR | 91-DAY | 182-DAY | 364-DAY |
OFFER (₦) | 100,000,000,000 | 100,000,000,000 | 600,000,000,000 |
SUBSCRIPTION (₦) | 19,181,113,000 | 23,017,438,000 | 1,079,100,705,000 |
ALLOTMENT (₦) | 18,116,113,000 | 22,282,437,000 | 672,905,704,000 |
BID RANGE (%) | 15.0000 – 16.3000 | 15.0000 – 18.0000 | 15.0000 – 18.5000 |
STOP RATES (%) | 15.4000 | 15.7900 | 15.8900 |
PREVIOUS STOP RATES (%) | 15.4000 | 15.7900 | 15.8000 |
FGN Bond Issuance Update: The DMO released a revised Q4 2026 issuance calendar, expanding the number of reopened instruments from three to four, with a strategic shift from medium- and long-dated to short- and medium-tenor securities, while retaining the monthly offer target at ₦2.00 trillion. The revised allocation ratio is 2.8:1:3:1.2 across the 21.00% March 2028, 19.30% April 2029, 17.945% August 2030 and 19.89% May 2033 bonds, respectively. Notably, the 2030 and 2033 instruments have each been issued twice in 2026, while the 2029 bond was last issued in July 2025, highlighting renewed emphasis on shorter-dated funding. Ahead of the November 16 auction, the total offer increased by 14.3% compared with the preceding auction, signalling a higher near-term domestic borrowing requirement. The increased supply could reinforce upward pressure on secondary-market yields, particularly if investor demand proves insufficient to absorb the additional issuance, although the eventual pricing and allotment will depend on prevailing market liquidity, investor appetite and prevailing yield expectations.
The Naira declined at the NFEM, depreciating by ₦4.63 (+0.34%) WtD and ₦7.18 (+0.53%) WoW, closing at $/₦1,353.97, compared with $/₦1,346.79 the previous week. Foreign reserves faced immense pressure, easing by 0.47% to $54.87 billion as of November 12, 2026, from $55.13 billion preciously. Blocked funds declined by 0.69% to $502.25 million, with the blocked-reserve ratio steady at 0.92%. The movements point to persistent external pressures on liquidity and FX conditions.
The Nigerian equity market staged a strong weekly recovery for the period ended November 13, 2026, with the NGX benchmark ASI climbing by +1.56% (+3,872.52 points) from the preceding week’s close of 248,877.22 points to settle at 252,755.29 points, expanding total market capitalization by ₦2.52 trillion to ₦164.80 trillion, and lifting the year-to-date (YTD) return to 62.42%. Daily sessions began on Monday with a +1.44% surge to 252,456.74 points (adding ₦2.32 trillion to settle at ₦163.92 trillion) anchored by rebounds in Dangote Cement (+9.61%, rising by ₦128.90 to ₦1,469.90 on strong 9M 2026 earnings following the prior Thursday’s circuit-limit drop), Transcorp Power (+5.65%), and Oando (+8.46%), before slipping -0.06% on Tuesday to 252,313.16 points (shedding ₦93.23 billion to ₦163.82 trillion) amid mild profit-taking in Tier-1 banks including First HoldCo, Stanbic IBTC, and Zenith Bank, and dipping another -0.18% on Wednesday to 251,861.24 points (losing ₦293 billion to ₦163.53 trillion) due to broad-based selling across Banking (-0.60%) and Consumer Goods (-0.15%) alongside a 10% drop in Okomu Oil. On Thursday, the market rebounded +0.20% to 252,366.80 points (recovering ₦328.26 billion to ₦163.86 trillion, as volume surged 596.70% to 2.91 billion shares valued at ₦78.66 billion across 28,318 deals, led by a 2.20-billion-share block trade in Livestock Feeds and ₦32.40 billion in First HoldCo) driven by renewed bargain hunting in Seplat Energy (+3.12%, following the publication of its Q3 dividend exchange rate), Stanbic IBTC (+2.55%), First HoldCo (+2.09%), Fidson (+9.94%), and Oando (+1.60%). The week concluded on a positive note on Friday, with the ASI advancing +0.15% (+388.49 points) to 252,755.29 points, supported by sectoral gains in Insurance (+4.44%), Industrial Goods (+6.11%), Banking (-0.21%), and Consumer Goods (+0.10%), and led by top advancers Caverton (+10.00%), Fortis Global Insurance (+9.93%), and Austin Laz (+9.91%), which outweighed declines in Multiverse Mining (-9.90%), LivingTrust Mortgage Bank (-9.69%), and eTranzact (-8.11%). At the same time, Friday turnover reached 3.69 billion shares valued at over ₦23 billion across roughly 27,145 deals, driven by Linkage Assurance (3.10 billion units) in volume and First HoldCo (₦7.33 billion) in value. Throughout the five sessions, selective institutional appetite navigated liquidity competition and roughly ₦5.85 trillion in total orders from the Dangote Refinery public offer as market participants awaited allotment and listing updates, alongside active mid-week positioning in Chams, Honeywell Flour Mills, and GTCO, even as cautious market breadth shifted from negative ratios on Monday (22 gainers vs. 34 losers, and 90 unchanged) and Wednesday (25 gainers vs. 33 losers) to positive territory on Thursday (28 gainers vs. 25 decliners) before finishing slightly positive on Friday (22 gainers vs. 24 decliners).
Global financial markets experienced heightened volatility amid a governance shockwave in the artificial intelligence (AI) and technology sector alongside a sharp hawkish repricing across global fixed-income markets triggered by diverging macroeconomic data. In the United States, hotter-than-expected October inflation, with headline consumer price index (CPI) rising 0.4% and core CPI up 0.3% month-on-month (MoM), combined with a 6.5% year-on-year (YoY) jump in October Produce Price Index (PPI) (the fastest annual wholesale pace since November 2022) to cement market pricing for a December Federal Reserve rate hike, propelling the U.S. 10-year Treasury yield reported up roughly towards to 5.14%–5.15% range, lifting the 2-year yield to 4.86%–4.88% level. The U.S. Dollar Index also strengthened against major currencies, reflecting changing interest-rate expectations and renewed demand for dollar-denominated assets. Across Europe, the Eurozone economy expanded by 0.40% quarter-on-quarter (QoQ) in Q3 2026, representing 1.3% YoY growth, compared with 0.6% QoQ in Q2, while UK real GDP increased by 0.7% QoQ in Q3 (up 1.9% YoY, supported by a 0.9% services gain). These developments influenced expectations surrounding the monetary-policy outlook of the European Central Bank (ECB) and Bank of England (BoE), while sovereign bond yields remained elevated. German 10-year Bund yields reportedly rose towards 3.35%, while UK 10-year gilt yields approached 5.30%. In Asia, China’s inflation data presented a mixed picture, with October PPI surging by 5.7% YoY, reflecting higher input costs and demand in select industrial segments, while CPI eased to 0.7% amid falling food prices. In global equities, Wall Street posted a strong overall weekly rebound (S&P 500 up 2.51% to 7,561.67; Nasdaq Composite up 2.3% to 25,136.27; Dow Jones up 2.1% to 52,347.55) despite a late-week semiconductor sell-off sparked by the sudden Thursday resignation of Nvidia CEO Jensen Huang. Huang stepped down after 33 years, with CFO Colette Kress named interim CEO and Harvey C. Jones appointed board chair, after revelations of his relationship with suspected Chinese spy Alice Huang (an executive at Singapore partner Megaspeed) were compounded by New York Times and Reuters reports exposing additional extramarital affairs with Nvidia VP Kimberly Powell and a second company employee. The crisis erased roughly $490 billion from Nvidia’s market value over the week (dropping it below $4 trillion), sank server partner Super Micro Computer by 11% amid DOJ chip-smuggling probes, dragged down rivals AMD (-8.7%) and Broadcom (-4.9%) during Friday’s broader chip rout, and cast scrutiny over Nvidia’s $189 billion in 2026 private AI investments (including Hugging Face and Anthropic), while lower tech exposure and $35.13 billion in weekly fund inflows helped propel Europe’s STOXX 600 to a record close of 666.58 earlier in the week.
Global commodity markets diverged sharply as crude oil benchmarks posted a second straight weekly decline while gold fell well below key psychological support. Brent crude traded near $92.45–$96.13 per barrel, and WTI hovered around $86.14–$88.65 per barrel, as a larger-than-expected 4.7-million-barrel build in U.S. crude inventories and softer fuel demand outweighed late-week supply jitters following reported tanker explosions in the Strait of Hormuz and President Donald Trump’s dismissal of an immediate diplomatic deal with Iran. Simultaneously, spot and futures gold tumbled from an early-week high above $4,114 per troy ounce to consolidate near $3,888.50–$3,987.00 per troy ounce on Friday, pressured by a hotter-than-expected October U.S. Consumer Price Index (CPI) print, which saw headline inflation rise 0.4% MoM, alongside hawkish Federal Reserve commentary that pushed 10-year Treasury yields above 5.10% and solidified market pricing for an 85%–87% probability of a December interest rate hike.
The coming week is expected to be data-intensive, with key global economic releases including October 2026 inflation reports for Canada and the Eurozone, the People’s Bank of China’s (PBoC) interest rate decision, and U.S. Industrial Production, Retail Sales and House Price Index data. These releases could influence monetary policy expectations, sovereign bond yields and broader market sentiment. Domestically, anticipated liquidity injections are estimated at over ₦3.64 trillion, comprising ₦1.95 trillion in OMO maturities, ₦1.11 trillion in NTB maturities and ₦635.84 billion in FGN bond coupon payments on the May 2029, 2032, and 2033. Meanwhile, the release of Nigeria’s October inflation report will also be a key market catalyst, as expectations of inflation moderation could strengthen prospects of lower stop rates, improve fixed-income valuations and support carry-trade opportunities, particularly where prevailing yields continue to offer attractive real returns. However, any improvement in investor sentiment will remain conditional on inflation dynamics, liquidity conditions and the CBN’s policy direction. The outcome of Monday’s FGN Bond Auction outcome will provide an important near-term indicator of fixed-income market direction.
Expected dividend payments include OKOMUOIL at ₦11.50 per share on November 17, UNILEVER at ₦2.00 per share on November 18, ETRANZACT at ₦0.125 per share on November 19, and BERGER at ₦0.50 per share on November 20, 2026.
By: Sandra A. Aghaizu
Oil sailed through waters of excess supply,
While distant tensions darkened the sky.
Gold lost its shine beneath rising rates,
As inflation reshaped investors’ fate.
One faced the weight of demand growing weak,
The other the interest rates markets now seek.
Two different paths, yet one common theme,
A market caught between pressure and dreams.
Sometimes the greatest market lesson is not in the rise or fall, but in understanding what moves them both.
Subscribe now to keep reading and get access to the full archive.