September 2026, Edition 3
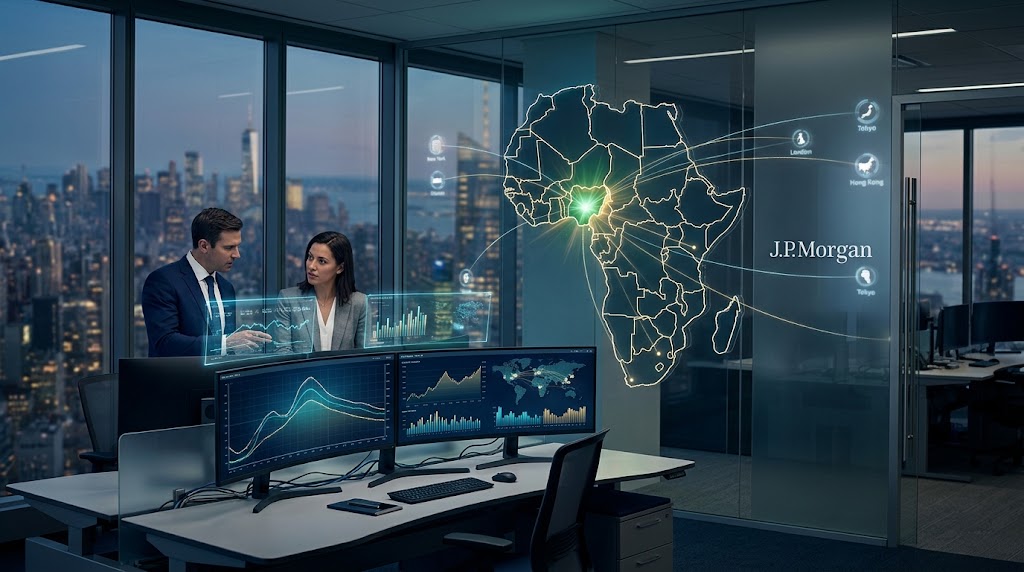
The launch of the J.P. Morgan GBI-EM Edge (EDGE) index is a major development for markets that have historically remained outside mainstream emerging-market local-bond indices. As of August 31, 2026, the index covers approximately US$328 billion of sovereign debt across 425 instruments, 26 markets, and 24 currencies. Regionally, Frontier Africa accounts for 44.5% of the index weight, followed by Asia at 31.5%. Individual country exposure is capped at 8%, limiting concentration risk while preserving meaningful allocations to larger frontier markets.
For Nigeria, the development represents a significant re-entry into the global local-currency fixed-income benchmark space following its 2015 removal from the flagship GBI-EM Global Diversified index amid foreign-exchange illiquidity. Nigeria holds a prominent position within the benchmark, carrying a 7.40% EDGE weight. This represents one of the largest allocations alongside a core tier of heavyweights including Vietnam, Egypt, Morocco, Pakistan, Bangladesh, Kazakhstan, and the Dominican Republic. Nigeria’s eligible universe comprises US$17.47 billion across 16 instruments, with an average yield-to-maturity of 17.1% and a duration of 3.38 years. Backed by an attractive carry profile, improving Foreign Exchange (FX) market functionality, and renewed foreign-investor access, Nigerian local debt stock is currently one of the more consequential African components of the index.
The significance of EDGE extends beyond another index launch. J.P. Morgan describes it as an attempt to establish a “Frontier beta” rather than simply a high-yield basket. Its methodology explicitly incorporates the practical constraints that have historically limited frontier-market investability, including convertibility, settlement, taxation, liquidity, and foreign-investor access. Eligible securities must generally be fixed-rate or zero-coupon sovereign bonds with more than 2.5 years of remaining maturity, an original tenor below 15 years, and at least US$250 million outstanding. This threshold is designed to capture the larger, more investable benchmark lines rather than artificially increasing the index with numerous technicalities.
The opportunity has expanded substantially: the EDGE universe has grown from about US$56 billion and 76 bonds at inception to roughly US$328 billion and 425 instruments, representing almost six-fold growth in eligible debt. J.P. Morgan estimates that the broader frontier local-debt segment has already attracted approximately US$10 billion in structural frontier-debt allocations, suggesting that EDGE is formalising an investment trend that was already developing.
Index-tracking funds and active managers benchmarked against EDGE will have an incentive to establish and maintain Nigerian local-bond positions. The immediate effect should be greater participation by foreign portfolio investors (FPIs) in eligible FGN securities, particularly benchmark maturities that meet the index’s size and maturity requirements. However, actual inflows will depend on replication strategies, the pace of index implementation, and investors’ assessment of Naira and liquidity risks.
Nigeria enters EDGE with one of the highest sovereign yields in the universe at about 17.1%, providing a substantial carry incentive. As foreign demand increases, eligible benchmark bonds should experience stronger bids, tighter spreads and potentially lower secondary-market yields. The impact is likely to be greatest in liquid 2.5–15-year securities rather than across every FGN maturity. This could improve price discovery and gradually reduce the government’s marginal local funding cost, although the extent of compression will depend on domestic liquidity, fiscal borrowing and monetary conditions.
The benefit is not simply a bond story; it is a currency story. J.P. Morgan’s back-tested data show that a 1% appreciation in the trade-weighted U.S. dollar has historically been associated with roughly a 0.7% decline in monthly EDGE returns, demonstrating the importance of FX translation for foreign investors. For Nigeria, sustained FX liquidity and orderly Naira price discovery therefore become central to retaining foreign capital. Interestingly, J.P. Morgan’s data show NGN FX performance improving to +6.7% in 2025 and +8.1% in 2026, a marked change from the severe depreciation recorded in 2023–24.
Greater offshore participation should increase turnover in eligible FGN securities, improve bid-offer conditions and strengthen the reliability of secondary-market pricing. For the broader market participants, this creates an opportunity to deepen Nigeria’s local fixed-income market and develop a more internationally investable yield curve.
Africa’s 44.5% EDGE representation is strategically important because it shifts the international investment narrative from predominantly hard-currency Eurobonds toward local-currency sovereign markets. Egypt, Nigeria, Kenya, Tunisia and Uganda are among the largest African exposures, while Angola, Zambia, Botswana, Ghana, Senegal, Niger, Namibia and Côte d’Ivoire also participate at smaller weights. The result is a broader African local-debt opportunity set spanning different monetary regimes, commodity exposures, fiscal positions and FX dynamics.
The performance evidence is also notable. Since inception, EDGE has generated 31.4% cumulative USD returns, or 3.2% annualised, compared with 18.3% for Global Bond Index Emerging Market (GBI-EM) Global Diversified, supported by an average nominal yield of 10.39%, approximately 443 basis points above the established benchmark. More than half of the index currently yields in double digits. Yet this return premium comes with materially higher dispersion and credit risk: the average difference between the best- and worst-performing markets is about 24.1% per month, versus 16.3% for GBI-EM GD, while the index’s current average credit rating is B+.
The EDGE inclusion should be viewed as institutional validation rather than a guarantee of capital inflows. Nigeria’s opportunity is to convert index eligibility into durable foreign participation by maintaining the conditions that made reintegration possible: transparent FX-market functioning, reliable repatriation, predictable settlement, credible monetary policy, and sufficiently liquid benchmark bonds. J.P. Morgan’s methodology explicitly allows a country to lose eligibility if severe investment restrictions or sanctions materially impair foreign access.
For the issuer, deeper secondary-market liquidity could eventually support a lower risk premium and more efficient long-term domestic borrowing, allowing a gradual shift away from excessive reliance on short-duration Treasury financing. For the Apex Bank, FX liquidity becomes even more consequential because local-bond demand from offshore investors creates a direct link between monetary credibility, currency stability, and sovereign funding conditions. For foreign investors, Nigeria offers
of EDGE’s strongest carry propositions, but the 17.1% yield will be interpreted alongside Naira volatility, sovereign credit risk and liquidity risk rather than as a risk-free return opportunity.
EDGE gives Nigeria and Frontier Africa something they have lacked at scale, a recognised institutional channel connecting local-currency sovereign debt to global portfolio allocation. The potential upside is deeper liquidity, stronger price discovery, lower funding costs and greater foreign participation. The policy challenge is equally clear: index inclusion can attract capital, but only sustained FX liquidity, market accessibility and macroeconomic credibility can keep it.

Subscribe now to keep reading and get access to the full archive.