September 30 – October 07, 2026
The crypto market entered October with a clear divergence in investor preference. Bitcoin (BTC) attracted renewed institutional demand and tested the $87,000 region, while Ethereum (ETH) struggled to sustain momentum, and the shutdown of Blast exposed growing pressure on the economics of Layer-2 networks. At the same time, regulatory developments, institutional infrastructure deals and tokenisation initiatives continued to strengthen the connection between digital assets and traditional finance.
The week’s price action suggests that the market is becoming increasingly selective. Capital is favouring assets with deeper liquidity, stronger institutional infrastructure and clearer long-term utility, while weaker protocols face growing pressure to demonstrate sustainable economics.
BTC traded within an approximately $83,700–$86,900 range, briefly clearing the important $85,000 supply zone before retreating. The move demonstrated meaningful demand, but the subsequent failure to establish $85,000 as firm support means the breakout remains unconfirmed.
Technically, the market is now defined by four key levels:
A decisive break above $87,200 could open the way toward $88,500–$91,200, while a sustained move below $82,500 would weaken the structure and expose Bitcoin to approximately $79,500–$81,000.
Fundamentally, Bitcoin continues to benefit from improving institutional infrastructure. BNY Mellon and Kraken parent Payward have discussed a potential partnership that could connect traditional banking infrastructure with digital-asset liquidity. The significance extends beyond a single transaction: deeper integration between banks and crypto-native platforms could reduce operational barriers for institutional participation.
Regulation is moving in parallel. The U.S. Securities and Exchange Commission proposed a framework addressing custody of crypto assets by registered investment advisers and regulated funds. The proposal, called ‘Adviser and Regulated Fund Custody Rules; Crypto Custody Rules,’ could broaden the role of regulated trust companies and other qualified custodial arrangements in institutional crypto markets.
However, the institutional expansion is generating regulatory competition. Community banking groups have challenged national trust charters granted to crypto companies by the U.S. Office of the Comptroller of the Currency, highlighting the growing contest over custody and financial-market infrastructure.
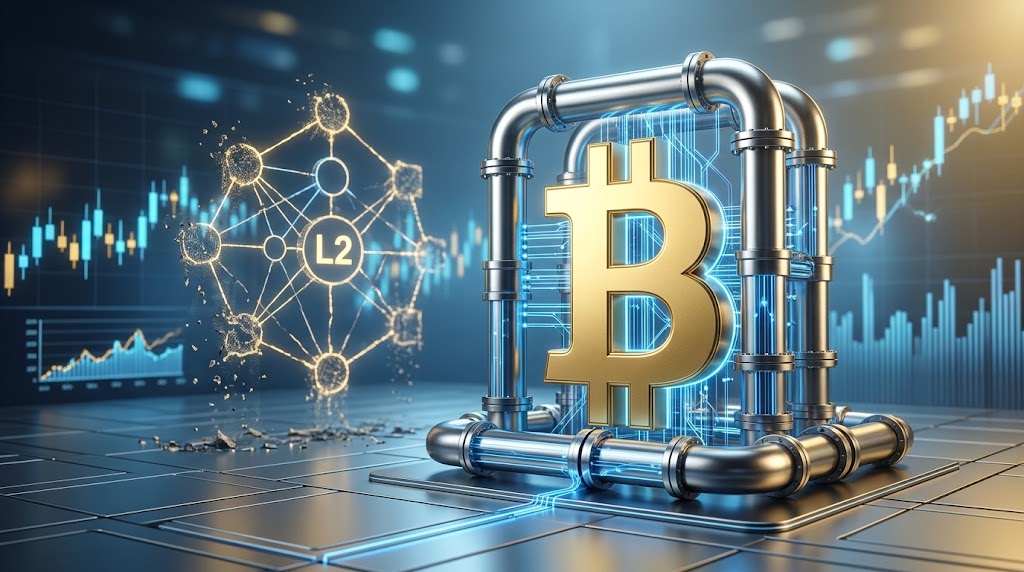
A clear indication that BTC’s next major leg may increasingly depend on institutional plumbing rather than retail speculation alone.
ETH remained comparatively subdued, trading around $2,680–$2,715 and struggling to establish a sustained position above the psychologically important $2,700 level.
The immediate technical test is therefore $2,700–$2,715, while a sustained recovery toward $2,850 would provide stronger evidence of renewed momentum. Conversely, a breakdown toward $2,520 would reinforce ETH’s current relative weakness.
Fundamentally, ETH’s development remains active. The Glamsterdam upgrade activated on the Sepolia testnet on October 6, introducing changes designed to improve Ethereum’s scalability and execution efficiency. Importantly, the activation is currently a testnet milestone rather than a mainnet deployment.
ETH’s infrastructure is also expanding beyond conventional Decentralized Finance (DeFi). The Ethereum Foundation introduced zkAPI, a zero-knowledge payment system designed to facilitate private payments for AI and metered API services. Such developments reinforce Ethereum’s broader ambition to become infrastructure for programmable finance, privacy-preserving payments, and machine-to-machine commerce.
The challenge is translating this technological progress into stronger economic value for ETH itself.
The closure of Blast, announced on October 2, was one of the week’s most significant structural developments.
Blast’s total value locked (TVL) had fallen sharply from more than $2 billion at its peak to approximately $32 million, while about $63.5 million remained in its canonical bridge. The project cited unsustainable operating costs and the absence of a viable path to economic sustainability.
Users have until October 26 to use the standard withdrawal interface, after which withdrawals will require direct interaction with bridge contracts.
Blast’s shutdown is significant because it highlights the transition occurring across the Layer-2 ecosystem. The first phase was characterised by aggressive growth, incentives, liquidity mining and rapid user acquisition. The next phase is likely to be defined by economic sustainability, transaction activity, security and genuine user demand.
A large TVL figure or successful token launch is no longer sufficient. Networks must demonstrate that their underlying economics can support infrastructure costs over time.
For investors, this creates an important distinction between technological relevance and investment viability.
Security continues to represent one of crypto’s largest structural risks.
The NEAR Intents ecosystem suffered an approximately $3.8 million exploit, linked to vulnerabilities involving its cross-chain infrastructure. The stolen funds were subsequently returned, but the incident again demonstrated the risks created by increasingly complex interactions between blockchains, bridges, liquidity providers, and smart contracts.
The approximately $387 million Bitget theft similarly highlighted the speed with which stolen digital assets can move through multiple chains and liquidity venues.
These incidents matter beyond their immediate financial losses. Institutional investors increasingly evaluate digital assets through the same lens applied to traditional financial infrastructure: custody, operational resilience, counterparty risk, governance and cybersecurity are now investment variables.
Consequently, investors cannot assess attractive yields or strong token narratives independently of infrastructure risk.
While speculative activity remains volatile, tokenisation is increasingly demonstrating real-world institutional relevance.
The UK government selected Barclays, HSBC, Lloyds, Morgan Stanley, NatWest and RBC Capital Markets to participate in its Digital Gilt Instrument (DIGIT) pilot, exploring distributed-ledger technology for sovereign debt issuance.
This development represents a broader shift in the digital-asset narrative. Rather than blockchain simply seeking to replace traditional finance, financial institutions are increasingly using blockchain technology to improve issuance, settlement, transparency, collateral management and liquidity.
The longer-term opportunity may therefore lie less in speculative tokens and more in the infrastructure supporting tokenised bonds, equities, funds, payments and financial assets.
Scenario | Trigger | Potential Market Response |
Bullish | BTC sustains closes above $86,000-$87,200 | BTC targets $88,500–$91,200; ETH could move toward $2,850 |
Neutral | BTC remains between $82,500-$87,200 | Consolidation and continued capital rotation toward BTC |
Bearish | BTC loses $82,500 decisively | BTC risks $79,500–$81,000; ETH could test $2,520 |
Systemic Risk | Further L2 failures or major exploits | Altcoins and DeFi could materially underperform BTC |
The bullish case strengthens if BTC converts $85,000 into durable support, institutional ETF demand remains positive, and liquidity continues to move toward spot markets. ETH would need to reclaim $2,850 to demonstrate meaningful relative strength.
The bearish case becomes more credible should BTC repeatedly fail at $86,000–$87,200 and break below $82,500, especially alongside rising derivatives liquidations or renewed macroeconomic pressure.
The crypto market is entering a more selective phase. And the central signal is therefore not simply bullish or bearish; it is selective. The market is gradually moving from narrative-led speculation to infrastructure-led financial integration, and that transition could define the next major cycle.
Tags:
By: Sandra A. Aghaizu
Ethereum builds beneath the ground,
While price moves slow, without a sound.
The engine grows, the road is clear,
But the market still needs to steer.
Technology plants the seed,
Momentum must follow if it is to lead.
Subscribe now to keep reading and get access to the full archive.