Period: September 23 – 30, 2026
The crypto market closed September 2026 in a consolidation phase, but the more important story was unfolding beneath price action. Rising U.S. Treasury yields constrained risk appetite, pushing Bitcoin (BTC) from above $84,500 toward $83,300–$83,400, while Ethereum (ETH) held around $2,670 and major altcoins softened. Yet institutional absorption remained evident as corporate treasuries continued accumulating digital assets, regulated derivatives expanded in the United States, banks accelerated stablecoin and tokenisation initiatives, and regulators sharpened the distinction between genuinely decentralised protocols and centrally controlled systems.
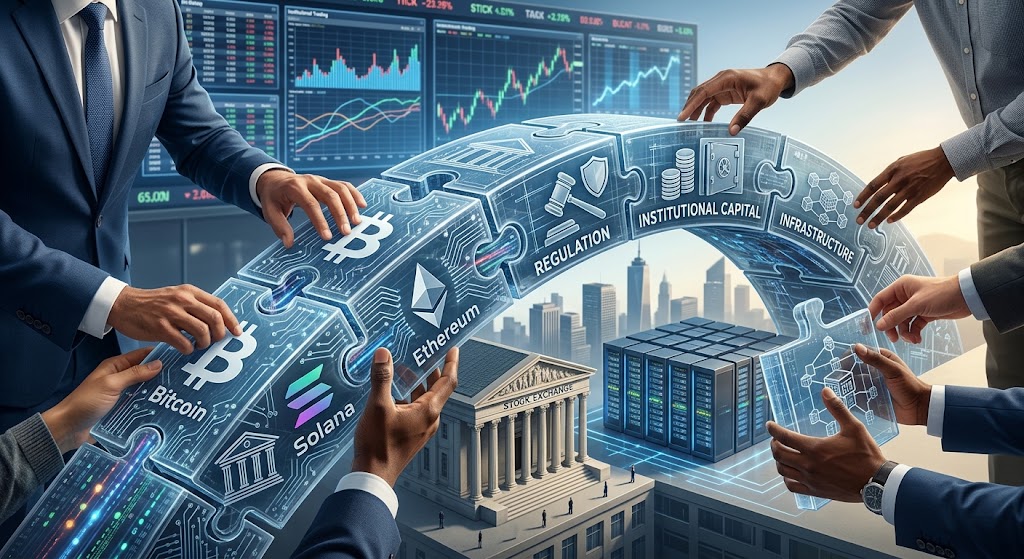
The week therefore reinforced a growing market reality: crypto is increasingly being shaped not only by token prices, but by the financial infrastructure, regulatory frameworks and institutional balance sheets surrounding those tokens.
Current level: ~$83,329 | Support: $80,000–$82,700 | Resistance: $84,500–$87,000
BTC’s attempt to sustain the $84,500–$85,000 area encountered substantial overhead supply as long-term U.S. Treasury yields climbed, with the 10-year reaching 5.21% and the 30-year touching 5.60%. The resulting tightening in financial conditions triggered renewed deleveraging across risk assets.
Nevertheless, the underlying institutional-demand narrative remains intact. Spot Bitcoin exchange-traded funds (ETFs) continued to attract capital during the month, while Strategy Inc. purchased another 1,665 BTC for approximately $142.7 million, taking its holdings to 847,666 BTC. The immediate technical question is whether BTC can defend $82,700 and absorb the supply around $84,500–$87,000. A sustained break below $82,700 would weaken the current structure and expose the $78,500–$80,000 region.
Current level: ~$2,669–$2,676 | Support: $2,620–$2,650 | Resistance: $2,700–$2,748
ETH remained range-bound around $2,670, with momentum constructive but losing some short-term strength.
More significant than the immediate chart is Bitmine’s reported accumulation of more than 6 million ETH, representing approximately 4.9% of total supply. The scale of the position reinforces institutional demand for ETH but simultaneously introduces concentration risk. ETH’s medium-term narrative is therefore increasingly tied to both network adoption and the behaviour of large corporate treasury holders.
Solana eased toward $118 as the market consolidated, while corporate treasury accumulation continued. DeFi Technologies Inc. (trading under the corporate treasury name DeFi Development Corp.) added approximately 47,706 SOL, taking its holdings to about 2.54 million SOL and SOL equivalents.
At the protocol level, Solana’s Alpenglow consensus upgrade progressed through public testing, targeting significantly faster finality. The development strengthens Solana’s infrastructure narrative, although a confirmed mainnet activation date remains outstanding.
Across the wider market, capital is increasingly gravitating toward infrastructure, payments and financial-market applications rather than indiscriminate altcoin exposure. This was reflected in continued financing activity around crypto infrastructure and prediction-market businesses.
One of the week’s most consequential developments was the continued migration of crypto derivatives into regulated U.S. infrastructure.
Robinhood moved to expand perpetual futures access for U.S. customers through its regulated derivatives structure, while Coinbase secured U.S. Commodity Futures Trading Commission (CFTC) registration for Coinbase Clearing. The significance extends beyond individual products: leverage that was historically accessed through offshore or less-regulated venues is increasingly being integrated into registered exchanges, futures commission merchants, and clearing infrastructure.
This could materially reshape crypto market structure. Regulatory registration, clearing, identity controls, and institutional risk management are becoming competitive advantages alongside liquidity and product breadth.
For permissionless platforms, particularly those without robust identity and compliance frameworks, the shift creates greater regulatory and capital-access pressure.
The U.S. Securities and Exchange Commission’s (SEC) September 28 update to its crypto FAQ added the phrase “and has no central party” to its guidance concerning token buybacks.
The change reinforces the importance of decentralisation in determining whether certain token-related activities could be viewed as involving managerial efforts under the securities framework. The practical implication is that issuers and protocols may face greater scrutiny over operational, economic and governance control.
For investors, this creates an additional diligence requirement: technical decentralisation cannot be assessed independently from governance and control structures.
Stablecoins are facing a similar transition. Tether reported assisting U.S. authorities in freezing approximately $550 million in USDT associated with Iran-linked networks following heightened scrutiny of sanctions compliance. The episode illustrates how stablecoin scale is increasingly accompanied by expectations around traceability, compliance, and enforcement cooperation.
Traditional finance (TradFi) continued to move beyond simply investing in crypto.
Citi expanded its partnership with Coinbase to support stablecoin payments for institutional clients, while a broader consortium of major banks is preparing a dollar-linked stablecoin initiative. Morgan Stanley also established a Digital Asset Lab focused on stablecoins, tokenised assets, DeFi and other blockchain-based financial applications.
The strategic implication is significant: major financial institutions are increasingly exploring blockchain as financial infrastructure rather than treating crypto solely as an investable asset class.
Corporate treasury accumulation reinforces the same trend. Strategy Inc. Bitcoin holdings, Bitmine’s large ETH position, and DeFi Development Corp.’s SOL treasury demonstrate the emergence of publicly listed companies whose balance sheets are directly exposed to digital assets.
This creates new institutional channels for crypto demand, but also introduces financing, governance, concentration, and corporate-execution risks.
The reported $387.5 million Bitget security incident provided a reminder that institutionalisation does not eliminate operational risk. The exchange attributed the incident to a third-party security vulnerability and said its cold-wallet infrastructure remained unaffected.
Meanwhile, the Compound governance dispute highlighted a different form of risk: the concentration of economic influence within supposedly decentralised systems. Questions surrounding the use of protocol reserves and delegated COMP voting power demonstrate why institutional investors increasingly need to examine not only smart-contract architecture but also governance concentration and treasury controls.
Decentralisation, in other words, is becoming both a regulatory question and an investment-risk question.
Constructive Scenario: A moderation in long-term Treasury yields could relieve pressure on risk assets and likely drive BTC to challenge the $84,500–$87,000 resistance band. Sustained ETF inflows and continued corporate accumulation would strengthen the absorption narrative. A confirmed breakout could reopen $87,500–$90,000, while ETH could retest $2,850–$3,000. Continued progress on Solana’s Alpenglow upgrade and expansion of regulated derivatives could support selective altcoin participation.
Downside Scenario: A further rise in long-term Treasury yields would maintain pressure on high-beta assets and potentially accelerate deleveraging. A decisive break below BTC’s $82,700 support could expose the $78,500–$80,000 region. For Ethereum, a failure to hold the $2,620 support level could see it slide toward $2,450, while Solana could retest key demand zones around the $105–$110 zone should macro conditions worsen. Additional regulatory action, governance disputes, or further exchange-security incidents could amplify risk aversion.
September’s final week demonstrated that crypto’s next phase may be defined less by speculative enthusiasm and more by institutional architecture.
BTC and ETH remain sensitive to global liquidity and Treasury yields, but the ecosystem around them is becoming increasingly institutional: regulated derivatives and clearing are expanding, banks are testing stablecoin settlement, corporate treasuries are accumulating tokens, and regulators are making decentralisation and control increasingly relevant to market access.
The result is a market undergoing structural consolidation rather than simple price consolidation.
The key question is no longer only where BTC or ETH trades next. It is which protocols, institutions, and financial rails will capture the capital, liquidity, and economic activity generated by the next stage of digital-asset adoption.
For investors, this makes fundamentals, regulatory architecture, treasury concentration, governance, and infrastructure increasingly important alongside technical price levels.
Tags:
By: Sandra A. Aghaizu
Loading…
Subscribe now to keep reading and get access to the full archive.